












 US Banks Launch BankChain Alliance for 2027 Blockchain Rollout
 Article Contributors
 Fact checked by
 Read Time: 1mins
 Published: 31/08/2026 | Updated: 08/09/2026


A Unified Platform for Regional Lenders
For years, smaller financial firms faced significant technical and capital hurdles when attempting to adopt distributed ledger capabilities. While Wall Street titans possess the capital to engineer proprietary ledgers, independent institutions risk being left behind as transaction volume moves toward programmable rails.
The formation of this new consortium addresses that technological divide. Under the leadership of interim chair Kathy Kraninger, who formerly headed the Consumer Financial Protection Bureau and currently leads the Florida Bankers Association, the initiative invites institutions of all scales to hold equity in the platform.
By pooling capital and operational requirements, participant institutions can deploy modern payment tools without constructing independent software frameworks from scratch.
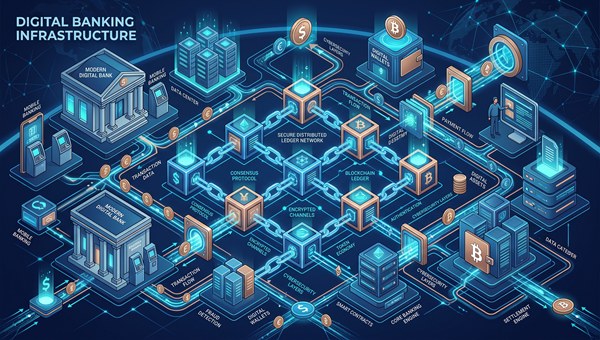
Dual Capability: Onchain Deposits and Regulated Tokens
The proposed system is being designed to support two distinct forms of digital value: bank-issued stablecoins and tokenized deposits. Although both mechanisms move value across distributed networks, their legal frameworks differ significantly.
Tokenized deposits remain direct balance-sheet liabilities of individual issuers, maintaining standard commercial protections. Conversely, stablecoins operate against segregated reserve holdings.
Rather than picking a single instrument, the network architecture will accommodate both modalities. This approach allows institutions to modernize transaction settlement speed while safeguarding the traditional customer deposit base that fuels localized business lending.
Navigating Technical Choices and Regulatory Alignment
Though the alliance has established a launch window targeted for 2027, several structural decisions remain ahead. The entity is presently selecting a technology provider and has not yet published specifics regarding consensus protocols, validator selection, privacy safeguards, or whether the system will utilize a private or permissioned framework.
Furthermore, the initiative arrives alongside parallel industry efforts, including major clearing house digital asset projects and emerging federal statutory guidelines such as the GENIUS Act.
To achieve operational readiness, the consortium must finalize governance terms, build cross-network interoperability mechanisms, and secure active participation commitments from individual lenders before full-scale testing can commence.


 eabungana@gmail.com

