












 Chainlink Unveils Enterprise Gateway to Swift Blockchain Ledger
 Article Contributors
 Fact checked by
 Read Time: 2mins
 Published: 02/10/2026 | Updated: 03/11/2026
Orchestrating Legacy Banking with Distributed Ledgers
Interbank messaging powerhouse Swift has taken another tangible stride toward blockchain adoption, introducing a dedicated technical gateway engineered alongside Chainlink.
Unveiled on September 28, 2026, the framework allows financial institutions to link internal core-banking databases and transaction-approval pipelines straight into Swift’s shared distributed record.
Rather than tearing down entrenched banking stacks, the deployment functions as an enterprise orchestration tier. It bridges internal software with distributed networks, translating instructions, triggering programmed condition checks, and updating shared records without disrupting standard day-to-day operations.
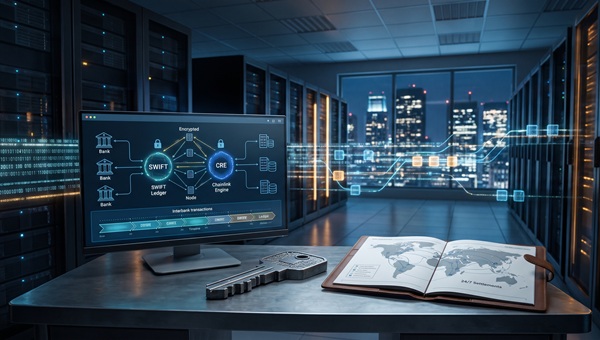
The Self-Signing Imperative: Keys Stay in Internal Vaults
For tier-one commercial lenders, third-party custody of cryptographic credentials represents an insurmountable regulatory hurdle. The technical linchpin of this rollout is its self-signing configuration, managed via the Chainlink Runtime Environment.
Under this design, institutions maintain sole custody of the digital keys authorizing every transaction. Dual-control authorizations, executive sign-offs, counterparty risk boundaries, and existing internal audits function exactly as they always have.
The runtime layer organizes the sequence of external events, automates condition evaluations, and dispatches data streams, but never usurps signature authority. This balance provides complete technical automation alongside rigid administrative sovereignty.
Around-the-Clock Liquidity Without Destabilizing Commercial Money
The primary use case driving this infrastructure is the mobilization of tokenized deposits. Unlike non-bank dollar-pegged tokens, these digital claims sit directly on the balance sheets of issuing institutions, preserving standard capital structures and commercial protections.
While tokenized assets reside on banks’ proprietary registries, Swift’s shared ledger coordinates interbank value transfers continuously—including overnight hours, weekends, and statutory holidays. Crucially, Swift continues its longstanding role as an orchestration and messaging infrastructure.
Definitive settlement continues through established clearing channels like real-time gross settlement rails, granting lenders frictionless round-the-clock liquidity without upending established regulatory frameworks.
From Sibos Prototype to Live Industry Trials
The shared ledger initiative matured rapidly, developing from initial collaborative designs presented at Sibos into an active environment within nine months. More than forty multinational lenders assisted in sculpting the technical specifications, culminating in seventeen founding institutions testing live pilots.
The participating vanguard spans global financial hubs across six continents:
- The Americas: Citi, BNY, Wells Fargo, Itaú Unibanco
- Europe & the UK: BNP Paribas, HSBC, Lloyds Bank, UBS
- Asia-Pacific: ANZ, DBS, MUFG Bank, OCBC, Standard Chartered, UOB
- Middle East & Africa: First Abu Dhabi Bank, Mashreq, FirstRand Bank
With Swift currently linking over 11,500 institutions across more than 200 markets, the integration represents a pragmatic pipeline for traditional capital markets to embrace decentralized ledger efficiency without abandoning the regulatory guardrails that preserve global financial stability.


 eabungana@gmail.com

